P.S. Free 2025 GARP 2016-FRR dumps are available on Google Drive shared by PrepAwayPDF: https://drive.google.com/open?id=11xP__FD48lb9JBzoBxAUHwOCflkV3G0D
Our three versions of 2016-FRR study materials are the PDF, Software and APP online. They have their own advantages differently and their prolific 2016-FRR practice materials can cater for the different needs of our customers, and all these 2016-FRR simulating practice includes the new information that you need to know to pass the test for we always update it in the first time. So you can choose them according to your personal preference.
GARP 2016-FRR Exam is an essential certification for risk professionals working in the financial industry. It provides a comprehensive understanding of financial risk management and regulation, which is crucial in today's rapidly changing financial landscape.
We understand our candidates have no time to waste, everyone wants an efficient learning. So we take this factor into consideration, develop the most efficient way for you to prepare for the 2016-FRR exam, that is the real questions and answers practice mode, firstly, it simulates the real 2016-FRR test environment perfectly, which offers greatly help to our customers. Secondly, it includes printable PDF Format of 2016-FRR Exam Questions, also the instant access to download make sure you can study anywhere and anytime. All in all, high efficiency of 2016-FRR exam material is the reason for your selection.
The Global Association of Risk Professionals (GARP) is a non-profit organization that is committed to promoting and advancing the risk profession worldwide. One of the primary ways that GARP accomplishes this goal is through its certification program, which includes the Financial Risk and Regulation (FRR) Series. The FRR Series is designed to provide professionals with a deep understanding of financial risk management and regulatory requirements.
NEW QUESTION # 60
A bank owns a portfolio of bonds whose composition is shown below.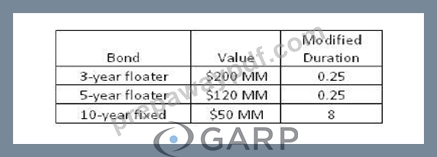
What is the modified duration of the portfolio?
Answer: C
NEW QUESTION # 61
A credit associate extending a loan to an obligor suspects that the obligor may change his behavior after the
loan has been originated. The obligor in this case may use the loan proceeds for purposes not sanctioned by the
lender, thereby increasing the risk of default. Hence, the credit associate must estimate the probability of
default based on the assumptions about the applicability of the following tendency to this lending situation:
Answer: C
NEW QUESTION # 62
Bank Alpha is making a decision about lending 10-year loans in a sector that is fairly illiquid and is looking at various options to fund the loans. Which of the following options to fund the loans exhibits the most exogenous liquidity risk?
Answer: B
Explanation:
Bank Alpha is making a decision about lending 10-year loans in a sector that is fairly illiquid. This type of lending requires stable and long-term funding sources to match the loan duration and illiquidity. Among the options provided:
* Overnight interbank markets: This option involves very short-term borrowing which needs to be rolled over frequently. The liquidity risk is high because the market conditions can change daily, making it the most exogenous liquidity risk as the availability and cost of funds can vary widely and unpredictably.
* The 6-month LIBOR markets: This is a short to medium-term funding option, still involving some liquidity risk due to the need for periodic refinancing, but less frequent than overnight markets.
* The 1-year treasury markets: Treasury markets are generally more stable and have lower liquidity risk compared to interbank markets. However, they still require annual refinancing.
* Foreign exchange markets: These markets add the complexity of currency risk along with liquidity risk.
Thus, overnight interbank markets exhibit the most exogenous liquidity risk due to the need for daily refinancing.
How Finance Works, relevant pages discussing liquidity risks associated with different funding options.
NEW QUESTION # 63
In additional to the commodity-specific risks, which of the following risks represent the main commodity
derivative risks?
I. Basis
II. Term
III. Correlation
IV. Seasonality
Answer: D
NEW QUESTION # 64
Which of the following statements regarding collateralized debt obligations (CDOs) is correct?
I. CDOs typically have loans or bonds as underlying collateral.
II. CDOs generally less risky than CMOs.
III. There is a correlation among defaults in the CDO collateral which should be considered in valuation of
these complex instruments.
Answer: A
NEW QUESTION # 65
......
2016-FRR Pass4sure Study Materials: https://www.prepawaypdf.com/GARP/2016-FRR-practice-exam-dumps.html
2025 Latest PrepAwayPDF 2016-FRR PDF Dumps and 2016-FRR Exam Engine Free Share: https://drive.google.com/open?id=11xP__FD48lb9JBzoBxAUHwOCflkV3G0D
